Loupe Signals New Era for Narrow-Web and Label Industry
2026-02-28

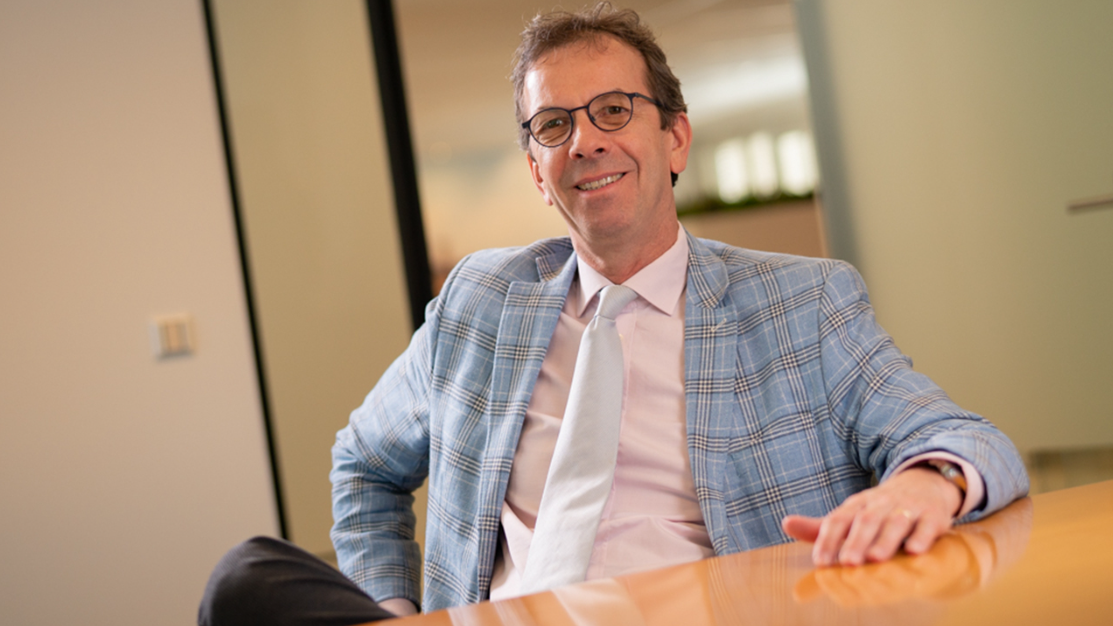
Image credit: Labels & Labeling
The rebranding of Labelexpo to Loupe is more than a cosmetic change—it’s a signal that the narrow-web and label industry is entering a new structural phase. According to Finat managing director Jules Lejeune, the shift mirrors how labels have evolved from simple self-adhesive products into integral components of modern packaging ecosystems.
At its core, Loupe represents convergence: the blending of technologies, materials, and applications that once operated in silos. For converters, suppliers, and brand owners, that convergence is redefining competitiveness.
From Self-Adhesive Labels to Integrated Packaging Layers
Over the past two decades, labels have transformed from a print-and-convert process into a high-value packaging layer responsible for branding, compliance, product protection, and increasingly, traceability.
This shift accelerated dramatically in the last 10 years. Shorter production runs, rising SKU complexity, and faster product turnover have forced converters to prioritize flexibility and repeatability. Press performance alone is no longer the differentiator.
Instead, workflow-led competitiveness has taken center stage. Automation, inspection systems, color management, and disciplined data processes now define operational excellence. In simple terms, the industry has moved from “printing better” to “working smarter.”
But perhaps the most profound change is structural. While self-adhesive labels remain the industry’s anchor, narrow-web technologies now extend into adjacent segments such as sleeves, in-mold labels (IML), pouches, and selected flexible packaging. These applications increasingly share the same technical backbone: similar substrates, finishing processes, digital workflows, and skill sets.
This convergence is precisely what Loupe aims to reflect.
European Market Reality: Stability Without Acceleration
From a market perspective, Europe is emerging from a turbulent cycle. In 2025, self-adhesive label materials consumption grew by 2%, roughly in line with GDP growth. That marked a shift from post-recovery momentum to recalibration.
Entering 2026, the market appears more stable—but growth remains modest and uneven.
Two structural signals stand out:
1. Application-Driven Demand Divergence
Variable information printing tied to logistics and distribution has proven more resilient than primary product labeling during periods of cautious consumer spending. In other words, supply chain labeling has been structurally stronger than consumer-facing packaging when retail demand softens.
2. Materials and Functionality Are Evolving
Sustainability requirements, performance demands, and traceability needs are reshaping substrate selection and functional design. “Proof” is becoming the new currency. Products must demonstrate recycling compatibility and compliance, not merely claim it.
For converters, that means documentation and verification now carry as much weight as print quality.
Three Trendlines Defining the Next Phase
Lejeune outlines three forces that will shape the narrow-web sector in the coming years—and they extend far beyond Europe.
Sustainability Moves From Strategy to Execution
Regulatory frameworks such as Europe’s Packaging and Packaging Waste Regulation (PPWR) are pushing companies beyond aspirational sustainability messaging toward measurable implementation.
Design-for-recycling compatibility, end-of-life scalability, and credible lifecycle data are becoming mandatory. And while Europe may be the regulatory catalyst, global brand owners are extending these requirements across their worldwide supply chains.
The implication: compliance readiness is no longer optional—it’s a competitive necessity.
Circularity Becomes a System Challenge
Circularity will not scale through isolated innovation. It requires viable collection systems, sorting infrastructure, recycling capacity, and end markets.
Finat, along with the Celab-Europe consortium it hosts, is working across the broader packaging and recycling ecosystem to ensure that technical solutions are scalable and compliant. Collaboration, as Lejeune emphasizes, is not a “nice to have.” It is strategic infrastructure.
This underscores a broader industry truth: no single converter or supplier can solve circularity alone.
Digitalization and AI Drive Productivity
Digital workflows are evolving from efficiency tools into core competitive assets. Short runs and SKU proliferation demand automation and data-driven process control.
Artificial intelligence is increasingly entering the conversation as a productivity lever—optimizing workflows, inspection, and operational predictability. Meanwhile, traceability is gaining importance not just for compliance but also for supply chain efficiency and circular systems.
In essence, data is becoming as critical as substrate.
Why Loupe Matters as an Industry Platform
Loupe’s relevance lies not only in its rebrand but also in its format.
Held every two years, it creates a concentrated industry moment where converters can see technologies operating live, compare solutions side by side, and translate strategy into investment decisions.
It is one thing to discuss convergence, automation, or circularity in theory. It is another to evaluate presses, finishing lines, inspection systems, software workflows, and sustainable materials in one place—alongside partners capable of implementation.
As embellishment grows in importance for brand differentiation and adjacent applications expand, innovation increasingly occurs at intersections: materials meet software, finishing meets compliance, and inspection meets data analytics.
Loupe aims to be the physical manifestation of those intersections.
The Bigger Picture: Connection as Competitive Infrastructure
Although Finat’s scope is European, the challenges it outlines—circularity economics, traceability requirements, supply-chain due diligence, and sustainability compliance—are global.
Loupe serves as a timely industry signal. Expectations are rising. Applications are broadening. Technological complexity is increasing.
The throughline is connection: between applications, between technologies, and across the wider ecosystem that makes high-tech, circular, and compliant packaging possible.
From our perspective at StoreTechNews, the rebranding represents more than a new name. It marks the recognition that narrow-web is no longer a niche print segment—it is a strategic layer within the global packaging and retail infrastructure.
And in an era defined by convergence, platforms that foster cross-disciplinary collaboration may prove as important as the technologies themselves.
Source: Based on reporting from Labels & Labeling